Prepay or Refinance? How to Choose the Cheaper Path
Extra payments and refinancing both save interest, but they win in different situations. How to decide which one actually saves you more.
Money···4 min read
Two ways to pay less interest
If you want to spend less on a loan, you have two main levers:
- Prepay: pay extra toward the principal so the balance (and the interest it accrues) shrinks faster.
- Refinance: replace the loan with a new one at a lower rate.
Both reduce total interest, but they're not interchangeable. The right choice depends on your rate, how long you'll keep the loan, and the fees involved. You can model your exact case in the prepay-vs-refinance calculator; this post explains the logic behind it.
How prepaying works
Every extra dollar toward principal removes all the future interest that dollar would have generated. Because interest is charged on the remaining balance, prepayments early in the loan save the most, because there's more time for the avoided interest to compound.
Prepaying is attractive when:
- Your rate is already decent, so refinancing wouldn't lower it much.
- You want flexibility: you can pay extra when you have spare cash and stop anytime.
- There are no (or low) prepayment penalties.
The tradeoff: your rate stays the same. You're shortening the loan, not repricing it. See the effect of different extra-payment amounts in the loan prepayment calculator.
How refinancing works
Refinancing swaps your loan for a new one, ideally at a lower interest rate. A lower rate reduces every future payment's interest portion for the life of the loan, which can be powerful on a large balance.
Refinancing wins when:
- Current rates are meaningfully below your existing rate (a common rule of thumb is ~0.5–1% lower, but it depends on the size and remaining term).
- You'll keep the loan long enough to recoup the closing costs.
- Your credit and income still qualify you for the better rate.
The catch is fees: closing costs, origination, appraisal. A refinance only pays off if the interest you save exceeds those costs, which brings us to the key number.
The break-even test
The deciding question for refinancing is the break-even point:
break_even_months = closing_costs / monthly_payment_savings
If you'll keep the loan (and the home) well beyond that many months, refinancing likely wins. If you might move or pay it off sooner, prepaying (with no fees and full flexibility) is often the safer bet.
- Closing costs$5,000
- The monthly payment drops$183from $2,026 to $1,842
- Months to win back the costs27 months$5,000 ÷ $183
A simple decision framework
- Is your rate well above today's rates? If yes, price a refinance and run the break-even.
- Will you stay past break-even? If not, lean toward prepaying.
- Do you value flexibility over a locked-in lower rate? Prepaying lets you start, stop, and vary extra payments freely.
- Any prepayment penalties or high closing costs? They tilt the math, so include them.
Often the answer is "a bit of both": refinance to a better rate and keep making modest extra principal payments.
Show the numbers
| Option | Saved |
|---|---|
| Pay $500 extra a month | $125,588 |
| Refinance to 5.5%, keep paying $2,526 | $168,471 |
| Refinance to 5.5%, pay the lower $1,842 | $50,008 |
Run your own numbers
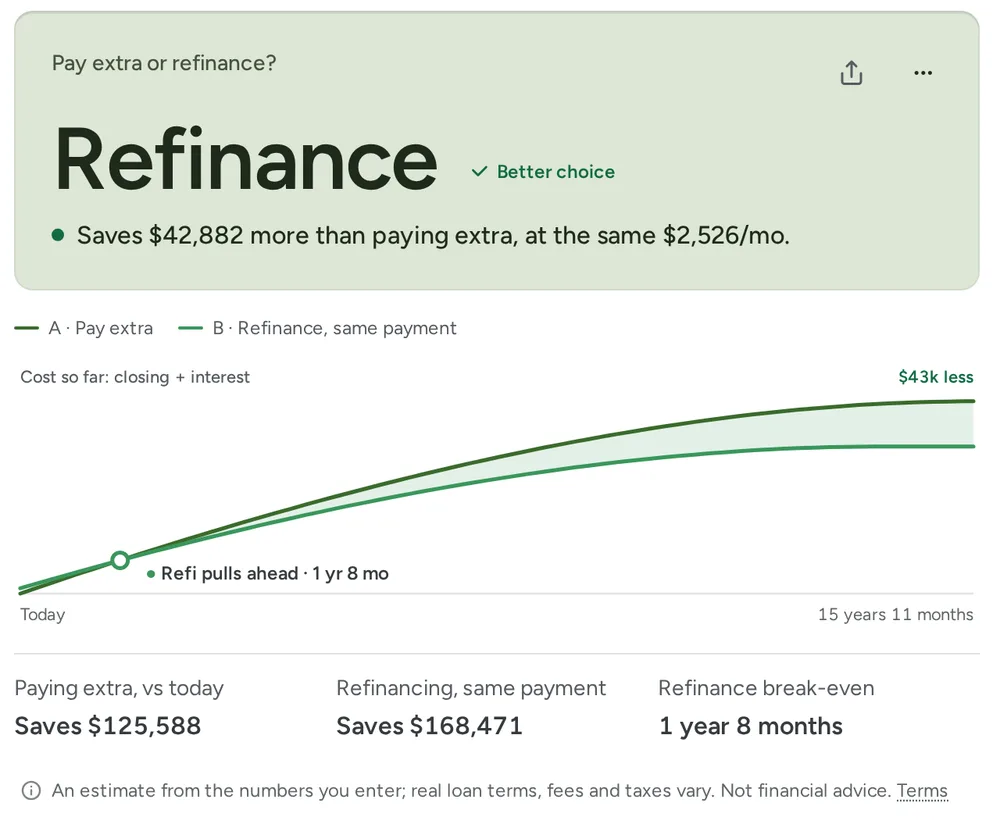
The calculator’s break-even is the month refinancing pulls ahead of paying extra, not of doing nothing, so it can come sooner than the simple rule above.
General rules only get you close. Your rate, balance, remaining term, and fees decide it, so compare both paths side by side in the prepay-vs-refinance calculator and see which one saves you more, in dollars, for your loan.
Share this post
Keep reading
Money· Nov 14, 2026· 12 min
How Much Do You Need to Retire Early? Your FIRE Number
Your FIRE number is 25 times a year's spending at 4%. We tested that rule on every US start year since 1871, including 50-year early retirements.Money· Nov 14, 2026· 8 min
What Is Coast FIRE? How Much You Need by Age
Coast FIRE is when your investments can grow to your FIRE number by 65 with no more saving. The formula, a table by age, and how often it worked since 1871.Money· Oct 24, 2026· 19 min· Updated Nov 2026
Are Solar Panels Worth It in 2026 Without the Tax Credit?
With the 30% credit gone for 2026 installs, a $21,000 system pays back in about 11 years at the US average power price and under 8 in California.